Dear Esteemed Client,
As we approach year-end, we want to help you get ahead of your 1099 filing obligations for payments made in 2026. There are some important changes this year, so please take a moment to review the highlights below.
What’s new: higher reporting threshold
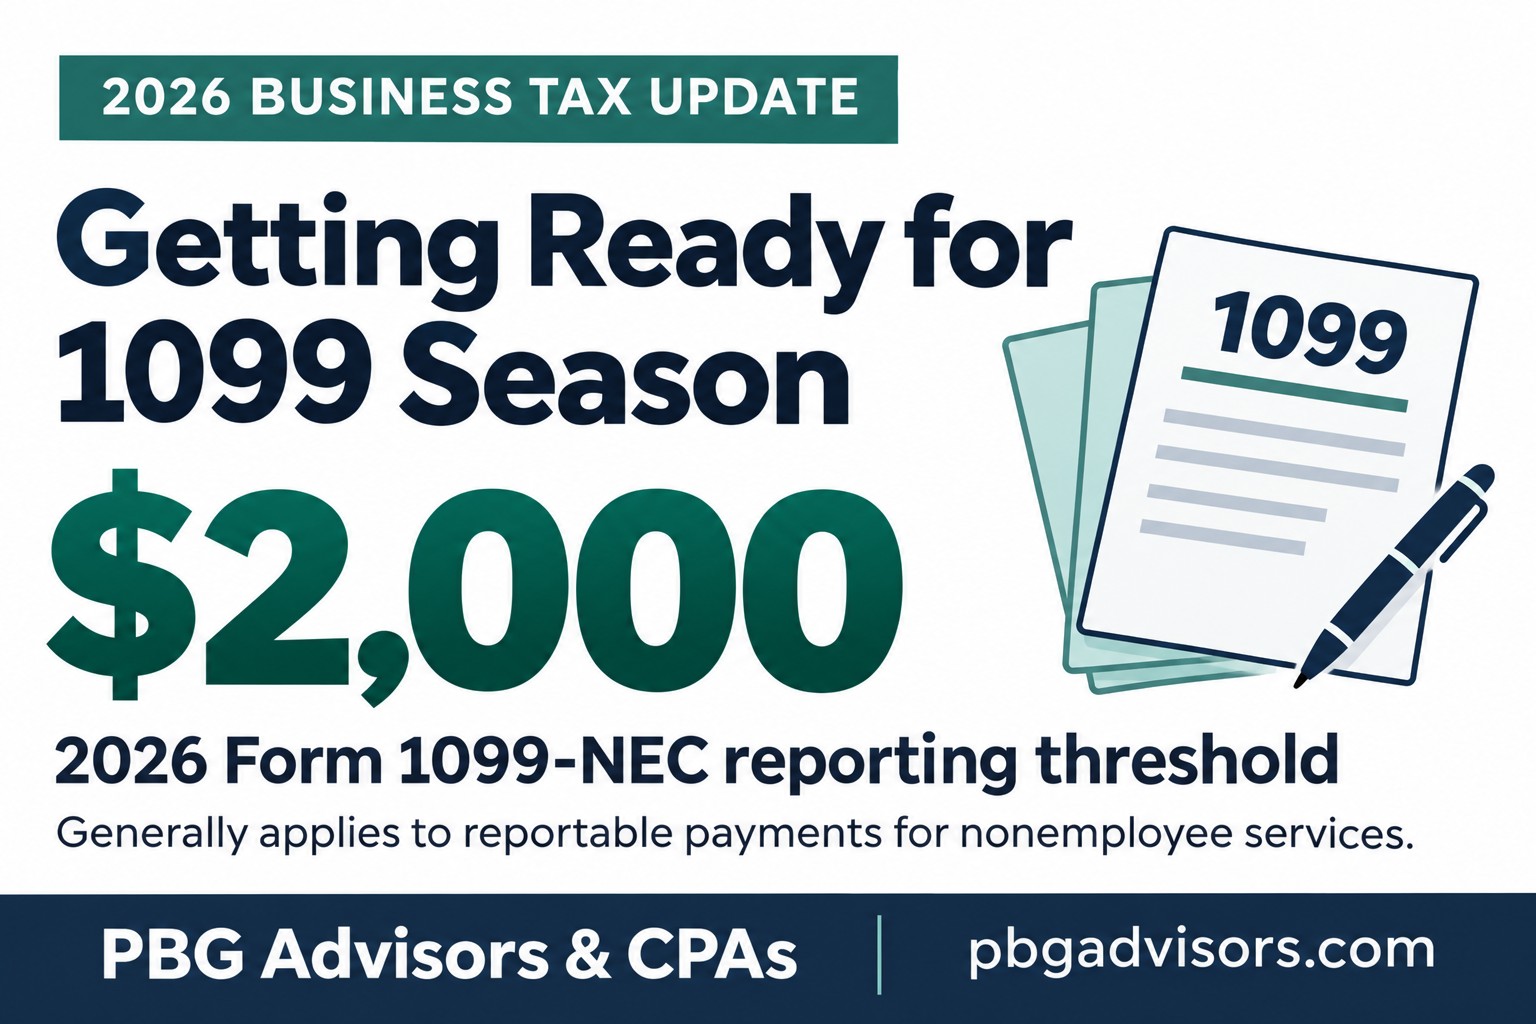
Starting with payments made in 2026, you generally need to issue Form 1099-NEC to each payee you paid $2,000 or more for services during the year, up from the long-standing $600 threshold. Once a payee reaches $2,000, you report the full amount paid, not just the portion above the threshold. The backup withholding trigger has also moved to $2,000.
When is a 1099 generally required?
Payments your business makes from your bank account for services or rent to partnerships or individuals (including single-member LLCs taxed as sole proprietorships) generally will require a Form 1099 when the applicable reporting threshold is met.
Payments made by credit card, or through payment apps (like PayPal) that fall under the Form 1099-K rules are generally excluded, since those processors report them separately on Form 1099-K.
Payments to corporations, including LLCs taxed as S or C corporations, are generally exempt, with notable exceptions for attorney fees and certain medical/health care payments.
Which form to use
– Form 1099-NEC: payments for services to vendors, independent contractors, freelancers, and attorneys.
– Form 1099-MISC: non-service payments such as rent, prizes, certain medical/health care payments, and other specified payments.
Backup withholding
You may need to withhold 24% from reportable payments if a vendor does not provide a correct taxpayer identification number or the IRS directs you to withhold. Special rules apply, refer the IRS instructions for Forms 1099-NEC and 1099-MISC for additional information.
Key deadline
-Form 1099-NEC is due to both the IRS and your contractors by February 1, 2027 (January 31 falls on a Sunday). Late or missing filings can result in penalties per form.
-Form 1099-MISC: Generally due to recipients by February 1, 2027, with exceptions for certain payment types. IRS filing is due March 1, 2027, if filing on paper, or March 31, 2027, if filing electronically.
What you can do now
– Collect a Form W-9 from every vendor and contractor you have paid this year, and from any new vendor before their first payment.
– Review your vendor list and payment records to identify who is likely to reach $2,000.
– Use each vendor’s Form W-9 to confirm their name, taxpayer identification number, and federal tax classification.
This is a general overview. Additional requirements and exceptions are explained in the IRS instructions for Forms 1099-NEC and 1099-MISC and IRS Publication 1099.
As always, feel free to reach out with any questions. We’re happy to help you sort out which payments are reportable.
For more answers to your frequently asked questions, please refer to our FAQ page.